Piezoelectric Actuators Market Snapshot

Key Players

  • Physik Instrumente (Germany)
  • PI Ceramic (Germany)
  • Aerotech Inc. (United States)
  • Cedrat Technologies (France)
  • Noliac A/S (Denmark)
  • APC International Ltd. (United States)
  • Sparkler Ceramics Pvt. Ltd. (India)
  • Nanomotion Ltd. (Israel)
  • Piezosystem Jena (Germany)
  • Piezomechanik GmbH (Germany)

Market Size

Base Year 2024
$1.64 Bn
CAGR
7.45%
Forecast 2034
$3.36 Bn

Market Segments

By Type
Stack Actuators, Bender Actuators, Ultrasonic Actuators, Tube Actuators
By Technology
Direct Piezoelectric Effect, Inverse Piezoelectric Effect, Piezoelectric Composites
By Application
Medical Devices, Robotics, Aerospace, Automotive, Consumer Electronics
By End Use
Industrial Automation, Healthcare, Telecommunications, Defense, Others

Market Dynamics

Drivers
  • Rising demand in precision mechanics
  • Innovation in nanotechnology applications
Restraints
  • High manufacturing costs
  • Limited material options
Opportunities
  • Emerging smart technologies
  • Increasing demand for precision control

Market Size

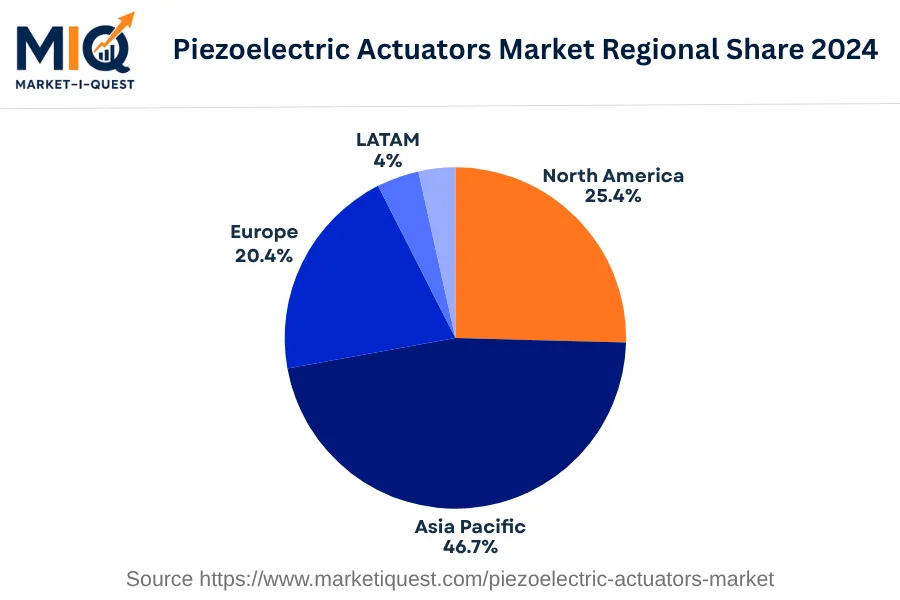
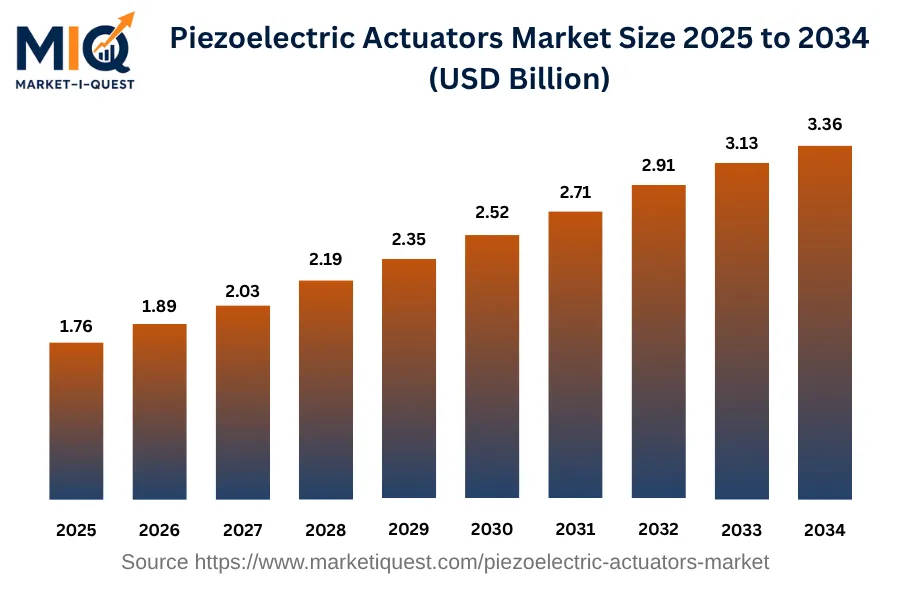
The Piezoelectric Actuators Market in the year 2025 valued at USD 1.76 Billion, which then increased to USD 3.36 Billion by the end of 2034, exhibiting a CAGR of 7.45%. The market indicated a steady rise over this forecasted period starting from USD 1.64 Billion in 2024. This growth was primarily fueled by the versatile uses of Piezoelectric Actuators across various industries such as automotive, aerospace and healthcare. However, the regional share distribution indicated North America holding a share of 25.4%, Europe had 20.4%, Latin America contributed to 4.01% and the Middle East and Africa accounted for 3.48%. However, the Asia Pacific dominated the market with a substantial share of 46.7%.

Key Takeaways

  • By Type - Tube Actuators secure the largest share in terms of revenue in 2024.
  • By Technology - Direct Piezoelectric Effect led the market accounting for a substantial portion of the total share in 2024.
  • By Application - Consumer Electronics held sway taking the spot for the highest market share in 2024.
  • By End Use - Telecommunications subsegment leads the market revenue as of the base year 2024.
piezoelectric-actuators-market market size

Key Driving Factors

Implementation of Strict Environmental Regulations

In many regions globally, such as the European Union and the United States, governments are enforcing stringent protocols for limiting the emission of greenhouse gases and promote energy-efficient solutions. Industries including automotive, manufacturing and aerospace are increasingly adopting piezoelectric actuators. Majorly due to piezoelectric actuators energy-efficient attributes, including their capacity for converting mechanical stress into electrical energy. This effective energy conversion results in less energy wastage, aligning with the enforced environmental regulations. Hence, industries are increasingly switching towards such efficient technologies, driving the demand and expansion of the piezoelectric actuators market.

Surge in Use in Precision Instrument Manufacturing

Precision instruments, such as microscopes, scanners, and medical devices, require components with high accuracy and reliability in their operation. Piezoelectric actuators, known for their high precision motion control capabilities, are being extensively used in manufacturing these instruments. They offer benefits such as high-speed operation, long service life and excellent resolution, making them ideal for precision equipment. Major companies involved in precision instrument manufacturing are heavily integrating piezoelectric actuators into their products, which is driving substantial growth in the piezoelectric actuators market.

Market Evolution by Timeline

2019-2023
During this period, the piezoelectric actuators market saw demand, particularly in Asia, driven by industries such as automotive and consumer electronics. Products, primarily manufactured by suppliers from China and Japan, offered improved force, precision and speed. The pricing model shifted towards the high-end due to the advanced technology, with contracts typically spanning multiple years. A prevalent barrier was the technical knowledge required for implementation, addressed by training programs and technical support by suppliers.
2024
For 2024, demand for piezoelectric actuators was reportedly stable. Applications expanded into AI and medical devices, primarily in developed economies such as the U.S. and Germany. Technology introduced during this year indicated better energy efficiency. While no specific regulations were enacted, guidelines for their use in medical devices were refreshed. As competition intensified, flexible pricing arrangements became more common, such as performance-based contracts. Difficulty in procuring certain raw materials posed a risk, partly reduced by exploration of alternative materials.
2025-2029
This five-year span will likely witness an increasing demand from emerging markets such as India and Brazil due to infrastructure development. The integration of piezoelectric actuators with IoT might set a trend during this period, albeit with challenges in reliable network connectivity. Countries are expected to begin for adopting guidelines on safety standards for piezoelectric actuators. Vendor partnerships might become a common model for supporting technology integration. An increasing risk of counterfeits will likely lead to concerns about quality assurance, prompting some for establishing in-house authenticity checks.
2030-2034
In this period, demand steady, with expansion into marine and space applications, particularly from institutional buyers such as NASA. Actuators will likely indicate enhanced durability and miniaturization. Environment-related regulations might begin influencing product design, driving companies towards using eco-friendly materials. Dominant pricing models are expected to involve long-term contracts with price escalation clauses allowing for inflation adjustment. The supply chain risk will likely increase due to geopolitical tensions, while addressing by diversifying sources across multiple countries.

Future Market Outlook

Future Opportunities

Current advancements in piezoelectric actuator technology offer promising future opportunities in various sectors. As smart manufacturing gains traction, the integration of piezoelectric actuators is expanding within robotics used in industrial automations, a trend witnessed since the implementation of Industry 4.0 strategies in manufacturing plants worldwide. There is a growing interest in eco-friendly and sustainable technology, driving manufacturers for exploring biodegradable piezoelectric composites. The aerospace industry’s increasing demands for lightweight materials presents another opportunity; companies such as Boeing are investigating piezoelectric solutions for actuation systems in aircraft structures for minimizing weight. The renewable energy sector is exploring the application of piezoelectric technology in energy harvesting systems, with pilot projects in Germany studying its effectiveness in converting mechanical energy into electrical energy from natural sources. The automotive industry’s drive for enhanced functionality in vehicles indicates avenues for piezoelectric actuators in active safety systems, as seen in recent models from Ford that utilize these devices. These developments indicate significant possibilities for further integration of piezoelectric actuators into diverse future applications.

Segmentation Analysis

By Type

The market is divided into subsegments including Stack Actuators, Bender Actuators, Ultrasonic Actuators, and Tube Actuators. Among these, Tube Actuators accounted for the largest revenue share while Ultrasonic Actuators are expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Tube Actuators

Market Share Leader

Tube Actuators secure the largest share in terms of revenue in 2024. This is largely attributed to the widespread application of these components in numerous industries, from healthcare to automotive, energy to robotics. Tube Actuators’ versatility, reliability and high capacity make them the go-to choice for many companies. Being significantly robust and easy to install, Tube Actuators are preferred in the manufacture of heavy appliances and for intensive tasks. Furthermore, the actuators' enhanced quality in load-bearing and weight capacity, as well as their extensive lifecycle, contribute to the increased demand, offering an elevated ROI to businesses. Regionally, the North American and European markets dominate, owing to their high-tech manufacturing sectors and substantial investments in R&D.

Fastest CAGR

Ultrasonic Actuators

Forecast Period Growth Leader

Ultrasonic Actuators are anticipated to have the most robust growth in the upcoming years. The rising interest in Ultrasonic Actuators can be attributed to their high-speed operation, precise control and low power consumption. These actuators seek growing adoption in various applications such as precision machinery and medical devices which demand high-speed, precise actuation. Although Ultrasonic Actuators are more expensive than other types currently, technology advancements and scale are expected to drive down prices, fueling increased adoption. Regulatory shifts towards energy-efficient and low-carbon technologies are also expected to rise growth in this segment. It's also crucial for monitoring the industry’s responses to these challenges and see whether new partnerships or policy incentives emerge for addressing them.

By Technology

The market is divided into subsegments including Direct Piezoelectric Effect, Inverse Piezoelectric Effect, and Piezoelectric Composites. In the base year 2024, Direct Piezoelectric Effect accounted for the largest revenue share while Inverse Piezoelectric Effect is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Direct Piezoelectric Effect

Market Share Leader

The Direct Piezoelectric Effect subsegment commands the largest share of revenue primarily due to its wide application and adaptability in various industries. This technology has found extensive use in the energy, automotive and medical sectors where its ability to convert mechanical stress into electrical charges has been indispensable. It is intrinsic in devices such as piezoelectric sensors and actuators. Its adoption is also driven by its relatively affordable cost of procurement and implementation compared to the other subsegments. Moreover, there is large-scale accessibility to this technology globally, as supply is not an issue. Further, the regulatory landscape is favorable with governments promoting devices that utilize such environmentally friendly technology.

Fastest CAGR

Inverse Piezoelectric Effect

Forecast Period Growth Leader

The Inverse Piezoelectric Effect is projected to register the fastest growth in terms of CAGR. Its growth is principally fueled by its increasing adoption in high precision industries including aerospace and medical technology due to its ability to produce mechanical displacement from an applied electric field. Technological breakthroughs and intensive R&D efforts have greatly enhanced the efficiency and accuracy of devices based on the Inverse Piezoelectric Effect, sparking additional interest. Constraints hindering its growth include limited awareness of its benefits and high initial capital expenditure. Nevertheless, strategic partnerships between technology providers, investors, and end-use industries can help catalyze its growth potential. However, the increasing adoption and ongoing technological innovation make it the subsegment with the highest growth potential.

By Application

The market is divided into subsegments including Medical Devices, Robotics, Aerospace, Automotive, and Consumer Electronics. In the base year of 2024, Consumer Electronics accounted for the largest revenue share while Robotics is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Consumer Electronics

Market Share Leader

While all segments play a crucial role in the market, Consumer Electronics significantly stands out in terms of revenue generation. This major lead is primarily due to the widespread use and high demand for electronic devices across the world. As technology continues to evolve, the trend towards smarter and more connected devices is driving the growth of the Consumer Electronics subsegment. Moreover, the influx of innovative products and technological advancements in the sector, such as AI-driven technology and IoT, further propels this growth. Geographically, regions with high disposable income and propensity to adopt new technology such as North America and Asia-Pacific, fuel consumption in this sector.

Fastest CAGR

Robotics

Forecast Period Growth Leader

Robotics exhibits the highest CAGR outlook. The demand for automation across various industries ranging from manufacturing to healthcare is significantly boosting the Robotics subsegment. The recent developments in Artificial Intelligence and Machine Learning have led to increased capabilities of robots, broadening their application areas and thus driving their demand. Additionally, the ongoing pandemic has acted as a catalyst, accelerating the integration of robots for contactless operations. Government initiatives and policies promoting automation and advancements in technology for reducing costs could help in overcoming these hurdles, thereby supporting growth in this subsegment.

By End Use

The market is divided into subsegments including Industrial Automation, Healthcare, Telecommunications, Defense, and Others. As of the base year 2024, the Telecommunications subsegment accounted for the largest revenue share while the Healthcare subsegment is expected to grow at the fastest compound annual growth rate (CAGR) during the forecast period.

Largest Revenue Share

Telecommunications

Market Share Leader

Telecommunications subsegment leads the market revenue as of the base year 2024, and this leadership can be attributed to several factors. The emergence of digitization, increasing internet penetration and rising demand for high-speed data services have been significant drivers in the growth. Customers are increasingly relying on telecommunication services for both personal and professional uses. In addition to this, the rapid expansion of technologies such as IoT and cloud services has necessitated robust telecom infrastructures. Furthermore, regulatory policies in many parts of the world encouraging digitization have also stimulated revenue growth.

Fastest CAGR

Healthcare

Forecast Period Growth Leader

Projected to grow at the fastest CAGR, the healthcare subsegment demonstrates promising potential. The escalating demand for improved medical services, advancements in telehealth, and the digitization of healthcare records have accelerated growth in this segment. Moreover, government regulations and policies encouraging the integration of technology into healthcare facilities have acted as growth catalysts. With substantial capital being invested in R&D and the adoption of innovative technologies, a rising trend of partnerships between tech companies and healthcare facilities is on the rise. The subsegment's high growth rate is driven by the emergent necessity of tech-integrated healthcare solutions, leading to high adoption rates and strong market intensity.

Competitive Analysis

Key Market Players

Manufacturers / OEMs

Physik Instrumente (PI)
Germany
PiezoDrive
Australia
Noliac A/S
Denmark

Key Suppliers & Raw Materials

Harris Corporation
US
Arkema Group
France
Kyocera Corporation
Japan

Distributors, Integrators & Channel Partners

Aerotech, Inc.
US
Elliot Scientific Ltd.
UK
Thorlabs, Inc.
US

Porter’s Five Forces Analysis

This analysis outlines the competitive forces in the Piezoelectric Actuators Market.

Supplier Bargaining Power

Medium

Limited number of material suppliers can impact piezoelectric actuator production costs.

Buyer Bargaining Power

High

Massive demand from technology OEMs promotes high buyer influence.

Threat of Substitutes

Low

Unique operation and characteristics make substitute products unlikely.

Threat of New Entrants

Medium

Technical knowledge barrier partially mitigates but capital-intensive manufacturing requirements present.

Competitive Rivalry

High

Many global firms vie fiercely, leveraging efficiency and innovation.

Regional Analysis

Geographic market dynamics and growth opportunities across key regions

Global Market Outlook

piezoelectric-actuators-market market regional share

North America

In 2024, the North American piezoelectric actuators market experienced marked growth, driven by a number of distinct factors. Technological advancements played a critical role, as innovations in miniaturization and system integration spiked the demand, particularly in sectors like healthcare, automation, and precision machinery. Increased investment in research and development, especially in the United States, also stimulated market growth. Further, the reinforcement of green energy policies in Canada and Mexico greatly incentivized the use of piezoelectric actuators, which are known for their energy efficiency and minimal environmental impact. Shifting trends also influenced the market landscape. There was notably a rise in partnerships and mergers & acquisitions, as firms sought to expand their market reach and capitalize on the unique strengths of their partners. Customer preference saw a significant lean towards compact and lightweight products, leading manufacturers to reevaluate their design strategies. A marked shift in distribution channels was also observed with a stronger emphasis on e-commerce platforms.

In terms of market segmentation, the enterprise, manufacturing, and healthcare sectors emerged as leading customers. The governments in North America, too, invested significantly in piezoelectric actuators for infrastructure development and defence applications, underscoring the broad range of applications that these devices offer. Overall, both drivers and trends indicate a robust growth trajectory for the piezoelectric actuators market in North America in 2024.
Asia Pacific

In 2024, the Asia Pacific Piezoelectric Actuators Market exhibited a remarkable surge in demand in diverse industries. High-chip integration, expanding communication infrastructure, and advanced robotics found in China and Japan have driven the demand for miniaturized devices leading to an upswing in the piezoelectric actuators market. Regulatory measures such as India's National Electric Mobility Mission Plan 2020 supported the industry's growth by intensifying electric vehicle production, which utilizes these actuators for precise tensioning and positioning of automotive parts. There's also strong supply dynamics from the South Korean manufacturers with cost-competitive pricing.

Key trends shaping the market include shifts in buyer preference, escalating towards lightweight, efficient, and compact piezoelectric devices. Developments in nanotechnology, especially in Australia's leading research institutions, accentuated the need for nano-precision applications in biomedical and precision mechanics sectors. Further, strategic partnerships have become prevalent. Notably, ASEAN manufacturers formed alliances with Chinese firms to access advanced technology and improve production. Market standards are strictly enforced, particularly Japan's RoHS directing the materials used in electronic devices. Consequently, these factors have molded consumer interface, quality assurance, and product designs across the key sectors such as manufacturing, telecommunication and healthcare.

Europe

In 2024, Europe's Piezoelectric Actuators Market observed increased dynamism, fueled by an array of factors. Major drivers included intensified demand from sectors like healthcare, automotive, and manufacturing. Stricter regulatory standards in environmental sustainability bolstered the market, as piezoelectric actuators’ energy-efficient properties became more appealing. Technological advancements in micro and nano-electromechanical systems also pushed market growth. Investments in research and development by key European countries such as Germany, France, and the UK further stimulated supply dynamics.

In contrast, market trends were influenced by customer preference for precision and miniaturization, which inspired manufacturers to develop more compact and effective piezoelectric actuators. Technological advancements led to a shift toward more sophisticated piezoelectric materials, like single crystal. In addition, an increased focus on channel partnerships and M&A within the market was noted, fostering market consolidation and growth. Enforced regulations on energy efficiency and noise reduction across industries such as automotive, aerospace, and manufacturing played a crucial role in shaping buying behavior and market trends. Particularly in Germany and the UK, new government policies prioritizing energy-efficient technologies had a tangible impact, positioning these countries as flag-bearers of the piezoelectric actuators market in Europe.

Latin America

In 2024, the Piezoelectric Actuators market in LATAM saw a moderate growth, driven by various demand factors and regional dynamics. Increased interest in miniaturization technology, particularly in Brazil, fueled demand for piezoelectric actuators in sectors such as automotive, healthcare, and telecommunications. Argentina and Chile introduced favorable regulations aimed at renewable energy generation that stimulated the adoption of piezoelectric devices in power harvesting. Furthermore, Mexico's high-precision manufacturing sector saw increased investment leading to a surge in demand for these actuators.

Several noticeable trends marked the 2024 market landscape for Piezoelectric Actuators in the LATAM region. Notably, increasing buyer preference for energy-efficient products influenced product technology and development. The consolidation of the telecom industries in Colombia and Peru, including partnerships and M&As, resulted in higher procurement of piezoelectric actuators. Enhanced enforcement of environmental standards across LATAM, particularly in Brazil and Argentina, pushed manufacturers to adopt environmentally-friendly production technology, steering the market trend towards green piezoelectric solutions. Due to these drivers and trends, piezoelectric actuators in 2024 found application across a variety of sectors, including government-led infrastructural projects, retail POS systems, and particularly in the enterprise sector where the demand for compact, reliable, and energy-efficient components was significant.

Middle East & Africa

In 2024, the market for piezoelectric actuators in the Middle East and Africa was primarily driven by increased technological adoption in various sectors and demand patterns. The surge in investments across Saudi Arabia, UAE, and Qatar's oil and gas industries led to heightened demand for high-precision applications, instigating growth in the piezoelectric actuators market. Similarly, tighter regulations regarding energy efficiency in South Africa and Kenya stimulated a higher implementation rate of piezoelectric actuators in utilities and manufacturing sectors. Aggressive technology adoption, particularly in Israel's healthcare sector and Egypt's telecom industry, further strengthened market growth.

Trends observed in 2024 included heightened buyer preference for miniaturized devices in Nigeria's financial services sector and medical fields in Egypt and South Africa. A significant technology shift was visible as industries in Saudi Arabia and UAE transitioned towards smart structures incorporating piezoelectric actuators over conventional systems. The dissolution of partnership barriers in Qatar, Saudi Arabia, and UAE led to an influx of key global market players, fostering market growth. The overall shift was further regulated by standardization policies, particularly in Israel and South Africa, ensuring the quality and safety of the piezoelectric devices. Accordingly, these drivers and trends played a significant role in shaping the piezoelectric actuators market landscape in the Middle East and Africa in 2024.

Recent Industry Developments

Latest market innovations, product launches, and strategic initiatives

April 2026

AUDIOWELL unveiled a next-generation piezoelectric air pump at the 40th China International Medical Device Design and Manufacturing Technology Exhibition (ICMD 2026). The device measures 21×19×3.2 mm, weighs 3.5 g, and delivers output pressure ≥40 kPa, targeting wearable medical devices and portable diagnostic instruments.

January 2026

Cedrat Technologies launched the new Pla05 and Pla25 linear power amplifier series designed for piezoelectric actuators, featuring CE certification and full compliance with EU safety, health, and environmental standards.

Frequently Asked Questions