Managed Services Market Snapshot

Key Players

  • IBM (United States)
  • Fujitsu (Japan)
  • Wipro (India)
  • Atos (France)
  • Accenture (Ireland)
  • NTT DATA Services (Japan)
  • Tata Consultancy Services (India)
  • Computacenter (United Kingdom)
  • DXC Technology (United States)
  • Cognizant Technology Solutions (United States)

Market Size

Base Year 2024
$348.45 Bn
CAGR
11.72%
Forecast 2034
$1055.48 Bn

Market Segments

By Service Type
  • Cloud Services
  • Managed Data Center Services
  • Managed Security Services
  • Managed Collaboration Services
  • Managed Mobility Services
  • Network Services & Testing
  • Others
By Organization Size
  • Large Enterprises
  • SMEs
By Vertical
  • BFSI
  • IT & Telecommunication
  • Retail & E-commerce
  • Healthcare
  • Industrial/Manufacturing
  • Energy & Utilities
  • Education & Research
  • Others

Market Dynamics

Drivers
  • Rising demand for specialized expertise
  • Increasing need for cost efficiency
Restraints
  • High implementation costs
  • Resistance towards IT outsourcing
Opportunities
  • Increased demand for outsourced IT services
  • Advancements in cloud technologies

Market Size

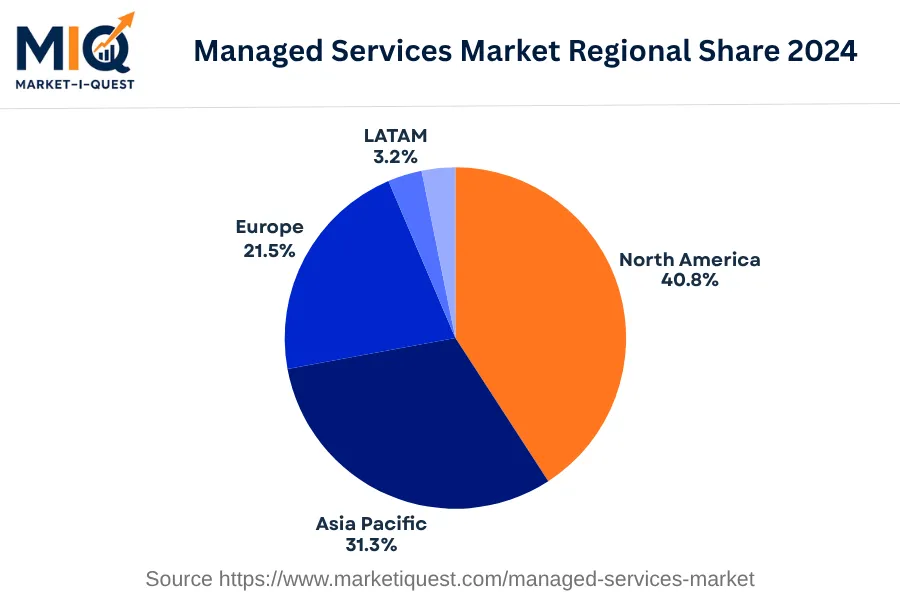
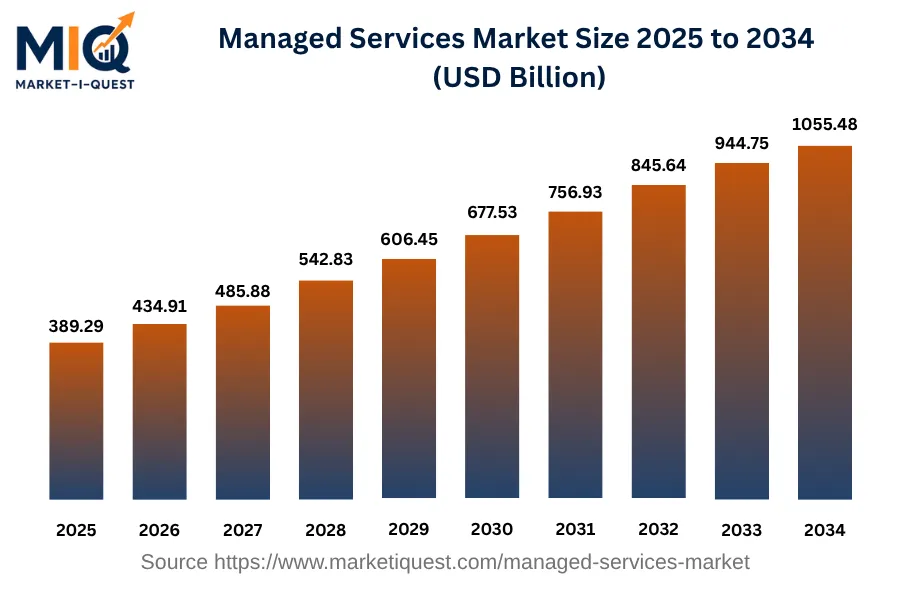
The Managed Services Market was sized at $389.29 billion in 2025 and is projected to reach a remarkable market valuation of $1055.48 billion by 2034, growing at a CAGR of 11.72%. This substantial growth pattern commences from an initial value of $348.45 billion in 2024, setting off an ascending trend in market size through the decade. Integral to its expansion is a consistently increasing market value, as evident in the value progression from 2025 to 2034. Regionally, the Managed Services Market exhibits mixed share dynamics as of 2024. North America held the largest market share of 40.84%, closely followed by the Asia Pacific region with a 31.26% share. Europe claimed a 21.48% share of the market, while lesser market shares were commanded by Latin America and the Middle East and Africa, with 3.24% and 3.18% respectively.

Key Takeaways

  • By Service Type - Managed Data Center Services led the market accounting for the highest share in the base year.
  • In the Organization Size - Large Enterprises held the dominant position in the base year.
  • By Vertical - IT & Telecommunication industry was the leading sector in the base year.
managed-services-market market size

Key Driving Factors

Shift toward Operational Expenditure Model

The Managed Services Market is being positively influenced by the increasing preference of companies towards an operational expenditure (OPEX) model over a capital expenditure (CAPEX) model. In an OPEX model, companies pay for services as and when they use them, leading to cost efficiency and allowing for more financial predictability. Managed services providers offer various services under an OPEX model including IT infrastructure management, security solutions, and cloud-based services, which appeal to companies looking to streamline their resources and reduce costs.

Increased Regulatory Compliance Requirements

Another significant driving factor for the Managed Services Market is the escalating complexity of regulatory compliance across various sectors. Industries such as healthcare, finance, and utilities are subject to stringent and continually evolving regulations. Companies operating in these sectors are increasingly outsourcing their compliance management to managed services providers who have the expertise and the technology necessary to stay updated with changes in regulations. These services steer the companies away from potential fines and reputational damage linked to non-compliance. Thus, the need for specialized services to manage regulatory compliance is propelling the growth of the managed services market.

Market Evolution by Timeline

2019-2023
During this period, the Managed Services Market saw IT service providers and SMBs from North America and Europe as predominant buyers, driven by needs for cost optimization and efficient process management. Technological supply included predictive analytics and automation platforms, with some shortfalls in integration capabilities. Regulations under GDPR and California Consumer Privacy Act influenced adoption, requiring customer data management conforming to privacy standards. The commercial model was typically subscription-based, with one-off project fees in customized services. An uptick in cloud partnerships, with AWS and Azure, was noticed as a response to SaaS adoption acceleration. As the supply side fell short on specialist skills, cybersecurity saw increased outsourcing.
2024
In 2024, the market for Managed Services saw a spike in demand from Asian countries, with medium to large scale businesses driving this trend. The need for operational efficiency and data security were primary reasons. AI and Machine Learning became indispensable components for service providers, however, integration with diverse enterprise systems was still a challenge. Policies revolving cyber security and data protection, such as China's Personal Information Protection Law, affected the market. Services were usually priced on a usage-based model with multi-year contracts being commonplace. To mitigate these, companies sought local partnerships, which was deemed typical.
2025-2029
Demand in the 2025-2029 period is expected to direct towards big data processing and analysis, mainly from industries like healthcare and finance globally. The General Data Protection Regulation (GDPR) and new data sovereignty regulations may affect this market, enforcing localized data storage. Usage-based and subscription pricing models with optional add-ons will likely be common. The market is expected to witness the partnerships with technology vendors to offer comprehensive solution packages. Providers may turn to investing in in-house expertise and alliances to manage this.
2030-2034
During 2030-2034, adoption of Managed Services expected to surge with demand from growing digital economies in Africa and South America. The need for specialization in industries like agriculture using IoT and advanced analytics might shape the supply. Commercial models will likely involve enterprise deals with long-term contracts for larger clients and flexible usage-based pricing for SMBs. Responses might include collaborations between service providers and cyber security firms to overcome threats, while in-house training developed expert personnel in anticipation of emerging technologies.

Future Market Outlook

Future Opportunities

The increasing complexity of IT environments presents future opportunities for managed service providers. Organizations continue to grapple with multi-cloud strategies that involve utilizing services from various cloud providers. As a result, MSPs can provide expertise in synchronizing operations across these diverse platforms. Well-recognized companies such as Accenture and Deloitte are already positioning themselves as leaders in managed cloud services, capitalizing on this growing demand for integration. The emphasis on sustainability is also transforming the managed services market. For instance, the International Organization for Standardization (ISO) released a new standard aimed at promoting environmentally sustainable practices in IT. Compliance with such regulations may create additional opportunities for MSPs that prioritize green IT solutions. The rising emphasis on skills development in technology, especially concerning cybersecurity and cloud management, opens avenues for MSPs to offer training services to organizations seeking to upskill employees. Furthermore, the increasing reliance on virtual and augmented reality technologies in various industries signals a need for specialized managed services to support these tools. With notable partnerships, like the collaboration between VMware and NVIDIA announced managed services sector has the potential to expand its scope and capabilities to meet the evolving demands of clients across diverse industries.

Segmentation Analysis

By Service Type

The market is divided into subsegments including Cloud Services, Managed Data Center Services, Managed Security Services, Managed Collaboration Services, Managed Mobility Services, Network Services & Testing, and Others. Within these, Managed Data Center Services accounted for the largest revenue share while Cloud Services is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Managed Data Center Services

Market Share Leader

Managed Data Center Services hold the largest share in the service type market due to several factors. The growth of data and businesses' need to effectively manage, process and store this data has increased demand for Data Center Services. Additionally, the emergence of Big Data and advancements in data analytics have made businesses more dependent on such services. The fact that data centers provide improved IT operations, increased data security, lower costs, and better scalability plays a significant role in their popularity. Geographically, regions with a high concentration of technology and business service providers have seen a greater uptake of these services. Regulations such as GDPR that enforce better data management are also a driving factor in markets within their jurisdiction. Important purchasing criteria for these services are reliability, security, the ability to scale, and cost-effectiveness. Heightened competition in this market has led to better service quality, helping to retain customers and posing significant switching costs.

Fastest CAGR

Cloud Services

Forecast Period Growth Leader

Cloud Services holds the tile for the fastest-growing segment. This growth can be attributed to several influencing factors. The digital transformation wave, fueled by advancements in technology, is pushing businesses to adopt cloud services. This technology provides a cost-effective solution for businesses to store, manage, and process their data. Moreover, it provides businesses with agility and scalability to match the changing market dynamics. Policymakers' growing emphasis on data security and privacy is further promoting the growth of secure cloud solutions. Capital expenditure in cloud technology is increasing year after year, indicating its potential for future growth.

By Organization Size

The market is divided into subsegments including Large Enterprises and SMEs. Large Enterprises accounted for the largest revenue share, while SMEs are expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Large Enterprises

Market Share Leader

Large enterprises typically generate the most revenue due to their extensive infrastructural setups, wider geographical reach, and the ability to invest in advanced technologies. These firms possess the resources to readily adopt and integrate high-end market offerings, thus driving sales in this segment. Furthermore, the complexity of their operations often necessitates the use of advanced tools, leading to higher revenue from this segment. Also, compared to smaller firms, large enterprises have a broader customer base that further bolsters their potential for revenue generation. In addition, large organizations frequently face stringent regulatory requirements, prompting them to invest in reliable solutions that meet these regulatory standards, thus contributing to their high revenue share.

Fastest CAGR

SMEs

Forecast Period Growth Leader

Small and Medium Enterprises (SMEs) are positioned to be the fastest-growing segment due to numerous growth drivers. The rising wave of digitization, companies' need to streamline operations, and the demand for cost-effective solutions are key factors pushing SMEs towards higher CAGR. Additionally, technological advancements and policies promoting digital adoption in small businesses contribute to their growth. This segment's growth could be hindered by constraints like budget restrictions and lack of digital literacy. However, initiatives aiming to remove these barriers, such as government-sponsored digital literacy programs and partnerships offering affordable solutions, can help overcome these obstacles.

By Vertical

The market is divided into subsegments including BFSI, IT & Telecommunication, Retail & E-commerce, Healthcare, Industrial/Manufacturing, Energy & Utilities, Education & Research, and Others. The IT & Telecommunication subsegment accounted for the largest revenue share while Retail & E-commerce is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

IT & Telecommunication

Market Share Leader

IT & Telecommunication sector leading in revenue share. The uninterrupted digital transformation and the globally escalating demand for smart technologies. This vertical has shown a relentless evolution irrespective of geographies, driven by innovation, regulatory support, and the need to streamline operations for enhanced productivity. Rising cybersecurity concerns and a surge in remote working have soared the demand for advanced telecommunication infrastructure. Besides, the rapid growth of IoT, AI, and machine learning along with the growing data traffic asks for sophisticated IT solutions. It's also notable that the purchasing criteria in this segment often lean towards tech-advanced, customized, and secure solutions, which supports the premium pricing. Providers have harnessed multiple channels, both direct and indirect, to better reach their customers.

Fastest CAGR

Retail & E-commerce

Forecast Period Growth Leader

The Retail & E-commerce sector is foreseen to record the fastest growth. This surge can be primarily attributed to the massive transition from brick-and-mortar stores to online platforms, amplified by the pandemic. Consumers are increasingly embracing digital platforms for their convenience, variety, and competitive pricing. Technologies such as AI, AR, and personalized marketing are making the shopping experience more engaging. For instance, data privacy concerns, infrastructural requirements, and maintaining logistical efficiencies pose challenges. Government policies promoting digital literacy and internet penetration are acting as catalysts to this growth. Despite these, the long-term growth trajectory for this sector appears promising due to the consumers' changing shopping behaviors, technological advancements, and expanding global e-commerce.

Competitive Analysis

Key Market Players

Manufacturers / OEMs

IBM
US
Cisco Systems
US
Fujitsu
Japan

Key Suppliers & Raw Materials

Microsoft
US
Dell EMC
US
Oracle Corporation
US

Distributors, Integrators & Channel Partners

Hewlett Packard Enterprise Development LP
US
CenturyLink
US
Verizon
US

Porter’s Five Forces Analysis

Assessment of competitive dynamics in the Managed Services Market.

Supplier Bargaining Power

Medium

Diverse set of suppliers with unique expertise can demand higher prices.

Buyer Bargaining Power

High

Large numbers of IT firms to choose from increase buyers' bargaining power.

Threat of Substitutes

Low

Complexity and integration of managed services reduces substitutability.

Threat of New Entrants

Medium

Requires substantial investment and expertise, but opportunity exists due to increasing digital needs.

Competitive Rivalry

High

Presence of many global and regional players increases market competition.

Regional Analysis

Geographic market dynamics and growth opportunities across key regions

Global Market Outlook

managed-services-market market regional share

North America

In 2024, the North American managed services market was typified by increased demand from various sectors, technology acceptance, and investment activity. Drivers for this market growth was a massive growth in demand from large enterprise and public sector customers to cut costs and enhance their operations and efficiency. Growing cyber security threats are also spurring adoption as customers look for rock-solid, dependable cyber security solutions. According to data collected for this research by Synergy Research Group, the growth of regulations was also key. These regulations include US regulations, European regulations, and regulations in healthcare. Other trends in the managed services market include an extreme migration to cloud computing for businesses, brought about by utilities and manufacturing, increased demand for managed Network as a Service, which is related to the migration to remote working, and mergers and acquisitions, which are part of service provider’s strategies to meet the increased demand for these services.

There was also a rise in offerings labelled Security as a Service, related to increased data breach and protection concerns. According to the report, the retail industry added to the growth of managed services in response to the digitalization trend, primarily in relation to the management of e-Commerce hardware and infrastructure. The extended adoption of work from home policies solidified the industry's move to managed services that provide extensive IT support remotely. The industry had also embraced new standards like the NIST cybersecurity framework.

Asia Pacific

In 2024, the managed services market in the Asia Pacific region showed steady growth owing to several key factors. Demand – Market Drivers and Trends Technological innovations enabled savings and drove demand, with key markets like China and South Korea investing heavily in cloud computing and cyber security. Countries like Japan and Australia created regulations that favored the use of cloud based and cyber security services, catalyzing further investments in managed IT solutions. Simultaneously, supply side market forces showed a move towards cloud data centers locally, focusing on areas like data sovereignty and an increase in public-private partnerships in India and ASEAN countries. The high reductions in costs of tech deployment pushed the market for SMEs, further aiding the growth of this space.

Key market trends included outsourcing of non-core IT systems like healthcare services in Japan and Australia and manufacturing and utilities in China and ASEAN markets. Due to increased implementation of flexi-work arrangements and work from home, there was an increase in the demand for remote infrastructure management services. A lot of mergers and acquisitions was seen around South Korea and India, where large companies acquired niche firms. Compliance to data privacy and data protection requirements was intensified. Despite the variety in demand across sectors and countries, the thrust towards digitalization remained a common thread, shaping the managed service market's dynamics in 2024.

Europe

In 2024, the Managed Services Market in Europe saw marked growth across diverse sectors. The rising demand for effective IT operations, rising cyber security threats, and rising cloud usage were the major reasons. Especially, organizations in Germany, the UK, and France picked up the cloud adoption services significantly, which in turn increased the need to keep IT costs down and achieve maximum efficiency. The new GDPR regulation drove the demand, as many organizations sought the help of the experts to ensure the regulation's compliance.

Remote working grew as the digital transformation continued in all sectors Shift to outsourcing accelerated in SMBs with companies in Spain and Italy leading the way Companies in Benelux, the Nordics and Central & Eastern Europe formed strategic alliances to expand their service offerings St. Renewed interest in Managed Security Services in terms of policy enforcement and adherence and, consequently, monitoring of data privacy rules. Influence of digital channels was prominent, with increased usage of them by managed services providers for delivering their products and services to the customer.

Latin America

In 2024, the Managed Services Market in Latin America witnessed significant growth arising from a range of determinants. Demand was driven by the digital transformation of businesses, across sectors such as healthcare, retail, manufacturing, and enterprises in nations like Brazil, Mexico, Argentina, Colombia, Chile, and Peru. Reformatory regulations favoring data security and technological adoption infused vitality into this market. A sizable share of investment earmarked for IT services domain by governments and corporations amplified the supply dynamics, bolstering the provider landscape. Trend-wise, customer inclination towards cloud-based managed services, driven by cost-effectiveness and operational agility, was notable.

Enterprises demonstrated strong preference for integrated Managed Services Providers (MSPs) offering a suite of tech-oriented solutions, prompting MSPs to pursue partnerships and M&A for consolidation of services. Substantiating this trend was the policy enforcement by authorities, nudging businesses to adhere to stringent data security norms, thereby skewing their preference towards professional MSPs. The emergence of 'Security-as-a-Service' model became a prominent shift, where companies, especially in the retail and healthcare sector, outsourced their cybersecurity concerns to expert MSPs. Simultaneously, the uptake of AI and automation went mainstream in MSP operations, underlining a tech leap in the Managed Services Market across LATAM.

Middle East & Africa

In 2024, the Managed Services Market in the Middle East and Africa flourished due to increased digital transformation and heightened IT security needs. Factors driving this market expansion included heightened cybersecurity threats requiring upgraded IT infrastructure, government mandates for modern digital transformation, and growing local investments in disruptive technologies like AI and IoT. For example, Saudi Arabia strengthened its Vision 2030 digital agenda, boosting demand for managed IT services in sectors such as government, oil and gas, and financial services. Significant market trends encompassed an increased demand for cloud-based managed services, growing reliance on big data analytics and adoption of remote work models. Mergers and acquisitions became an important strategic choice for expansion in the region, with tech companies such as IBM and Etisalat leading in the United Arab Emirates.

Policy enforcement around data protection and cybercrime, notably in South Africa and Kenya, also shaped the market landscape. The exponential growth in e-commerce in Nigeria and Egypt saw retailers seeking robust IT systems, further stimulating the market. Similarly, telecom operators in Israel and Qatar prioritized managed services to improve network efficiency and streamline operations in 2024. Post-pandemic, healthcare organizations across the region increased digital transformation efforts, adding further impetus to the managed services market.

Recent Industry Developments

Latest market innovations, product launches, and strategic initiatives

June 2026

European managed services provider Claranet acquired UK-based Six Degrees, creating a combined business with 3,500 staff and revenues exceeding €650 million, bolstering capabilities in cloud, security, networking, and AI.

August 2025

OpenText unveiled a major evolution of its Secure Cloud platform for the APAC region, featuring automated provisioning, integrated task management, and improved reporting to help MSPs deliver comprehensive cybersecurity services with greater efficiency and scale.

Frequently Asked Questions