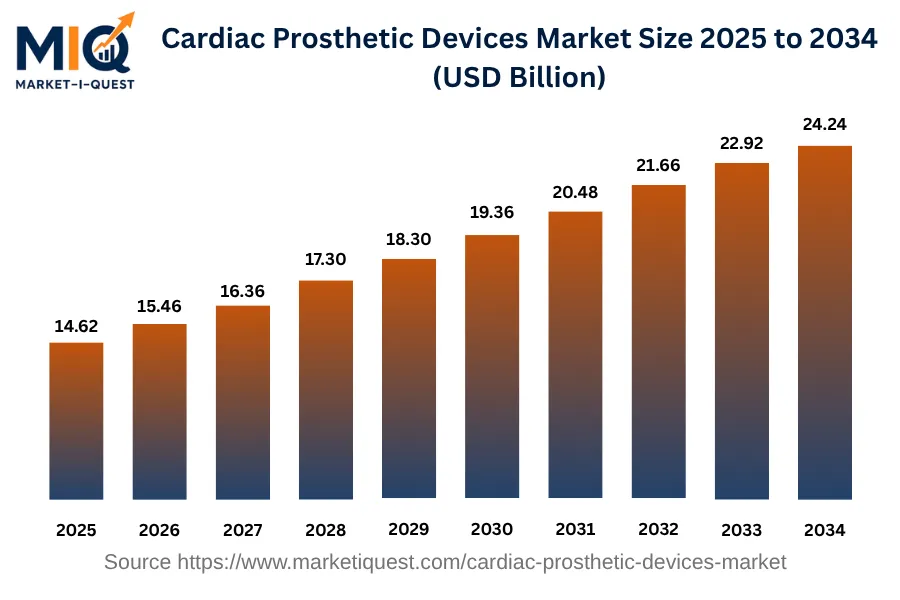
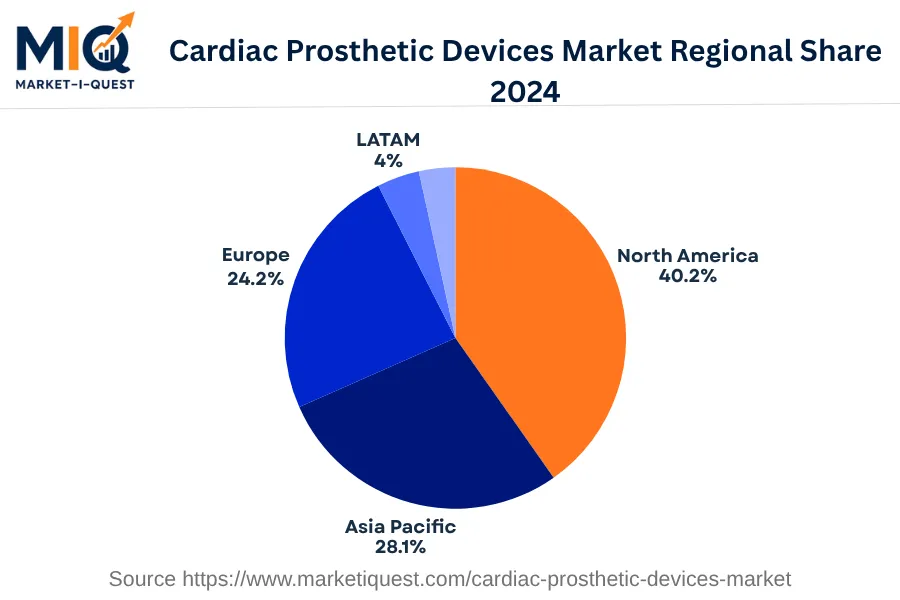
In 2024, the North American market for cardiac prosthetic devices exhibited substantial dynamism. Rapid advancements in medical technology, increased healthcare expenditure by governments, and a growing prevalence of cardiovascular diseases drove demand significantly across the region. In the U.S and Canada, favorable reimbursement policies facilitated an increase in cardiac procedures involving prosthetic devices, propelling market growth. Moreover, heavy investment in research and development activities within the biomedical sector spurred the creation of advanced, effective cardiac implants. Crucial trends impacting the market included a shift towards minimally invasive procedures and a growing preference for bioprosthetic devices, promoting patient wellbeing and reducing post-surgery complications. In the U.S specifically, regulatory emphasis on real-world evidence (RWE) helped accelerate device approvals and market entry. E-commerce adoption was another trend, with manufacturers utilizing online platforms to improve their distribution channels.
A notable industry development was Medtronic’s acquisition of LAA closure device manufacturer, Append Medical, to enhance their cardiac prosthetics offerings. However, in Mexico, inconsistent regulation enforcement complicated the market landscape, leading to variability in device standards. Key responding sectors included healthcare providers, government bodies investing in public health infrastructures, and manufacturing companies engaged in biomedical device production. The resulting need for cardiac prosthetics was most evident from increased use in hospitals, specialty clinics, and ambulatory surgical centers.