
Disposable Gloves Market Snapshot

Key Players

  • Top Glove Corp. (Malaysia)
  • Hartalega Holdings (Malaysia)
  • Kossan Rubber Industries (Malaysia)
  • Ansell Ltd. (Australia)
  • Supermax Corp. (Malaysia)
  • Sri Trang Agro-Industry (Thailand)
  • Kimberly-Clark Corp. (US)
  • Semperit AG Holding (Austria)
  • Cardinal Health Inc. (US)
  • Mölnlycke Health Care AB (Sweden)

Market Size

Base Year 2024
$13.95 Bn
CAGR
6.3%
Forecast 2034
$25.70 Bn

Market Segments

By Type
  • Natural Rubber
  • Nitrile
  • Vinyl
  • Others
By Application
  • Medical
  • Examination
  • Surgical
  • Food Service
  • Clean Room
  • Others

Market Dynamics

Drivers
  • Growing healthcare sector
  • Rising hygiene awareness
Restraints
  • Regulatory compliance challenges
  • Increasing raw material prices
Opportunities
  • Rising healthcare industry demand
  • Increasing hygiene awareness

Market Size

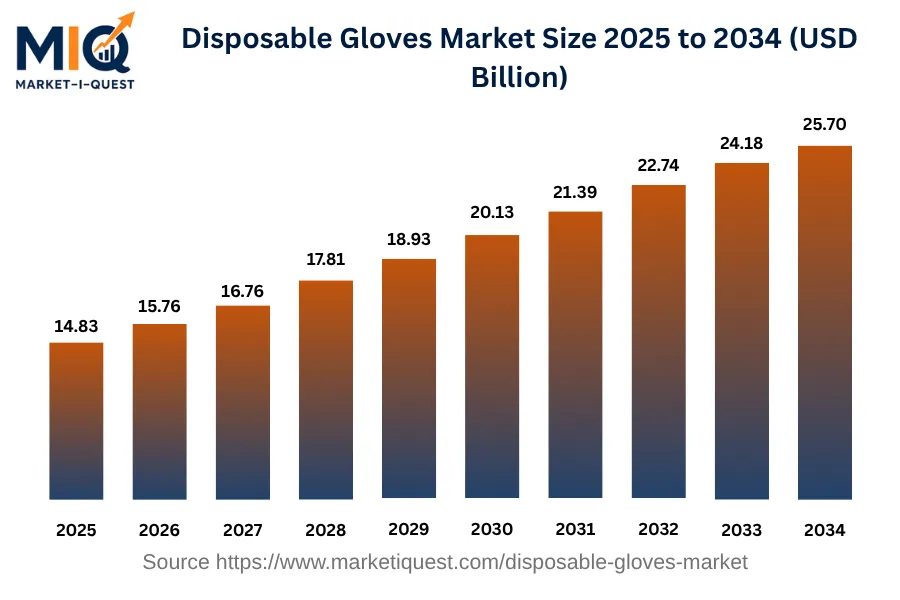
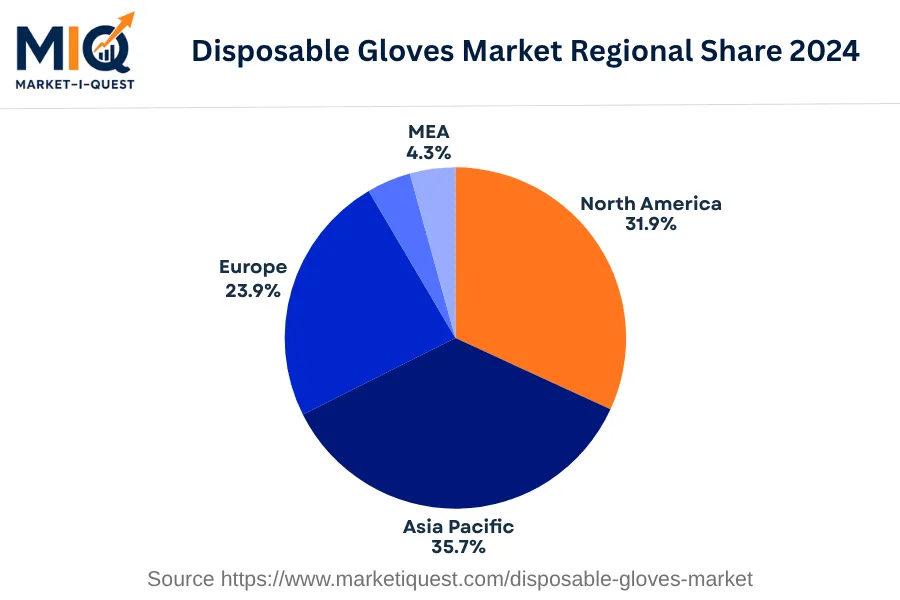
The Disposable Gloves Market size was 14.83 billion USD in 2025 and is projected to grow to 25.70 billion USD by 2034, charting a CAGR of 6.3%. This notable expansion from 14.83 billion USD in 2025 to 25.70 billion USD in 2034. A consistent rise in demand due to the demand of these products across diverse industries such as healthcare, food services and manufacturing sectors. The demand of the market is further increased due to the technological advancements, which have led to the production of improved quality disposable gloves providing better touch sensitivity and resistance to punctures and tears. However, the regional share distribution indicated, the Asia Pacific dominated the highest market share at 35.7%, followed by North America at 31.9%. Europe held 23.9% market share, while the Middle East and Africa (MEA), and Latin America (LATAM) accounted for 4.3% and 4.2% respectively.

Key Takeaways

  • By Type - Nitrile led the Disposable Gloves Market holding the greatest market share in 2024.
  • By Application - Medical segment held a leading position in the market in the given base year.
disposable-gloves-market market size

Key Driving Factors

Pandemic-led Hygiene Consciousness

The global Covid-19 pandemic has driven the consciousness for hygiene, health, and safety among individuals and organizations across various sectors. With specifically driving significant growth in the market. Businesses are now more likely to provide personal protective equipment, including disposable gloves, to their employees. This compliance to local and international safety standards, with maintaining a safe work environment enhancing the trust and commitment of employees. For industries such as food, healthcare and cleaning where hand hygiene is crucial, the use of disposable gloves has become a routine standard. Moreover, individuals are preferring the usage of disposable gloves for personal daily chores, outside work, shopping, or when using public transportation.
Rising Trends in Biodegradable Disposable Gloves

The rising concern over harmful environmental impacts driven due to non-biodegradable disposable gloves is driving manufacturers for shifting towards eco-friendly alternatives. The focus on innovating biodegradable disposable gloves, which are latex-free and degrade under natural circumstances, reducing carbon footprints. These eco-friendly gloves have gained significant interest from both businesses and consumers. This trend is driven by stricter regulations by environmental protective agencies globally for tackling non-biodegradable waste. Also investors are encouraging this shift by offering support to businesses that align with sustainable practices.

Market Evolution by Timeline

2019-2023
In this period, health care providers and food service workers from North America and Europe were main buyers of disposable gloves due to their familiarity with infection control procedures. There was a shift in supply as manufacturers in Asia, particularly Malaysia, increased their production capacities. The United Nations International Labour Organization (ILO) labor standards influenced adoption, prompting manufacturers to improve the safety of the workers. Most business transactions were conducted through long term contracts with fixed prices to secure stable supply. Practical blockers in this period were the high cost of raw materials, like latex and nitrile, forcing suppliers to increase their prices.
2024
In 2024, the demand for disposable gloves increased during the global covid-19 pandemic. Buyers from various regions indicated a demand for gloves, with increased usage in Asia and Africa due to its high rate of infection. However, the supply chain was disrupted due to lockdowns, causing a scarcity of gloves. Stringent safety and quality standards were implemented, such as ISO 13485 for medical devices. Prices of gloves increased due to high demand and limited supply, leading to short term contracts to manage volatility. The main risk was supply chain disruptions due to the ongoing pandemic.
2025-2029
In this period, the trend might shift towards non-medical sectors such as food processing and beauty services, especially in developing regions such as Asia and Africa. Manufacturers are expected to be fully recovered and the supply met the demand, shifting towards eco-friendly materials for complying with the 'Single-Use Plastics Directive' of the EU. This period will likely witness an adaptation to value-based pricing, with cost indicated by the type and quality of gloves, and partnerships with local distributors to increase market reach. The notable risk might br increasing regulations on plastic usage, encouraging research on alternatives to conventional disposable gloves.
2030-2034
By this phase, eCommerce might emerge as a significant channel for procurement, particularly for large healthcare institutions as well as industries such as food and automobile in developing markets of the U.S. and Europe. Notably, a rise towards smart disposable gloves with incorporated technology to monitor health metrics. The production process is expected mature, gradually integrating robotics and automation. As per regulatory standards, more firms might start complying with the 'Recyclables Directive' under the EU. Deal structure will likely change, favouring 'Pay-Per-Use' models. The major risk might remain the environmental impact and quest for viable alternatives.

Future Market Outlook

Future Opportunities

Various emerging opportunities may reshape its trajectory. The growing healthcare sector, highlighted by increased awareness of hygiene and infection control, fosters immense potential for manufacturers for expanding product lines. Countries such as India have increased healthcare infrastructure investments. Moreover, the food service sector is increasingly adopting disposable gloves to prevent cross-contamination, particularly during the ongoing pandemic, which has led industry bodies like the Food and Drug Administration to emphasize the importance of proper glove use in food safety. Companies are likely to pivot towards markets with high growth potential, such as chemical and automotive industries, where gloves are essential for protection against hazardous substances. Partnerships between glove manufacturers and technological firms, as exemplified by the collaboration between 3M and a tech company focused on developing smart PPE, signal a trend toward integrating technology with traditional protective gear. Moreover, as environmental regulations tighten globally, opportunities may arise for companies producing biodegradable gloves to capture market share among eco-conscious consumers. With the aging population and increased healthcare demands noted in regions like Europe, manufacturers can strategically position themselves to cater to these evolving needs.

Segmentation Analysis

By Type

The market is divided into subsegments including Natural Rubber, Nitrile, Vinyl, and Others. Nitrile accounted for the largest revenue share while natural rubber is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Nitrile

Market Share Leader

Nitrile subsegment has historically led in terms of revenue generation for several reasons. Foremost among these is the exceptional chemical resistance properties of nitrile compared to natural rubber or vinyl. This makes nitrile the preferred choice in many industrial operations where this trait is paramount before purchasing, despite its usually higher price. Moreover, nitrile's strength and tear resistance make it suitable for applications such as gloves in the healthcare sector. The frequency of these applications across diverse geographies contributes to its significant revenue share. Further, the rising consumption in the automotive industry for seals, hoses and belts due to its oil and fuel resistance capacities has also influenced the extensive usage.

Fastest CAGR

Natural Rubber

Forecast Period Growth Leader

Natural rubber holds the position of the fastest growing subsegment in the type segmentation. It's primarily driven by the increased demand across a variety of industries for products requiring elasticity, resilience and toughness. Main adopters included automotive, adhesives and construction sectors wherein natural rubber has found wide applications. The global shift towards more ecologically sustainable materials is a significant driver towards natural rubber's growth. Furthermore, technological advancements in processing and treating natural rubber have resulted in improved qualities, allowing its broader usability in weather-resistant products. Moreover, new partnerships between rubber producers and manufacturers, and the rising capital expenditure in rubber plantations.

By Application

The market is divided into subsegments including Medical, Examination, Surgical, Food Service, Clean Room, and Others. Out of these, the Medical subsegment accounted for the largest revenue share in 2024, while the Surgical segment is expected to grow at the fastest CAGR during the forecast period.

Largest Revenue Share

Medical

Market Share Leader

The Medical subsegment leads the pack due to multiple driving factors. The period heightened demand due to increased awareness in the wake of health crises. The rise in chronic diseases demanded frequent hospital visits, combined with a rise in the aging population, leading to a substantial increase in the demand for medical services. Moreover, global regulatory bodies' stringent compliance to safety standards in the medical sector is causing an increase in the usage of medical supplies. Recent innovations in the medical field, marked by product enhancements. The customers ranging from hospitals to home healthcare services have attributed the growth in this subsegment.

Fastest CAGR

Surgical

Forecast Period Growth Leader

The Surgical subsegment presents the fastest CAGR outlook. The primary drivers for this growth are technological advancements, growing partnerships within the industry and increased capital expenditure in healthcare. The adoption of minimally invasive surgeries and robotic surgeries driven by technological advancements has led to a rise in the demand for surgical supplies. Moreover, growing partnerships between hospitals, surgical centers and supply manufacturers are further accelerating this growth. The governments globally are significantly increasing their healthcare budgets and investing more in infrastructure. However, there could be obstacles in adoption linked to strict regulatory policies and the high cost of surgeries.

Competitive Analysis

Key Market Players

Manufacturers / OEMs

Ansell Limited
Australia
Top Glove Corporation Bhd
Malaysia
Hartalega Holdings Berhad
Malaysia

Key Suppliers & Raw Materials

Dynarex Corporation
US
Thai Rubber Latex Group
Thailand
Trinseo
US

Distributors, Integrators & Channel Partners

Medline Industries, Inc.
US
DACH Schutzbekleidung GmbH & Co. KG
Germany
Claflin Company
US

Porter’s Five Forces Analysis

This analysis gauges the competition dynamics and attractiveness of the Disposable Gloves Market.

Supplier Bargaining Power

Medium

Power is balanced by the existence of many suppliers but impacted by costs for raw materials.

Buyer Bargaining Power

High

Many alternatives and low switching costs give buyers high negotiation power.

Threat of Substitutes

Medium

Reusable gloves and automated processes pose a potential medium-level threat.

Threat of New Entrants

Low

High regulatory barriers and capital costs limit new entrants.

Competitive Rivalry

High

Multiple well-established companies lead to high market rivalry.

Regional Analysis

Geographic market dynamics and growth opportunities across key regions

Global Market Outlook

disposable-gloves-market market regional share

North America

In 2024, the North American Disposable Gloves Market presented a robust scenario driven by dynamic demand factors, technology adoption, and regulatory environment. High demand for disposable gloves was observed, significantly from healthcare and manufacturing sectors to maintain sanitation standards and prevention of potential hazards. Regulatory adherence to occupational safety boosted this demand, particularly in the U.S., as OSHA guidelines mandated safety glove usage in many industries. Increased investments in synthetic glove technologies revolutionized market supply dynamics, with U.S. manufacturers leading the way. E-commerce platforms offered new sales channels, altering purchasing behaviors while intensifying competition.

An emerging trend was the surge in eco-friendly disposable gloves, supported by the consumer shift towards sustainable products. Manufacturers increasingly participated in partnerships and M&A activities to expand their market presence and meet rising demand. Furthermore, the enforcement of FDA guidelines regarding glove quality in healthcare and food services sectors became more stringent in North America, significantly influencing manufacturing standards. The retail sector in Canada exhibited increased preference for nitrile gloves, favored for their high durability and allergy-free properties. In Mexico, notable growth in the manufacturing sector and increased awareness about workplace safety largely contributed to the rising consumption of disposable gloves.
Therefore, regulatory compliance, technological advancements, and shifting buying patterns governed the market trends and demands in the North American Disposable Gloves Market in 2024.

Asia Pacific

In 2024, the Disposable Gloves Market in Asia Pacific was marked by robust growth from various sectors including healthcare, manufacturing, and utility services. Drivers included the extensive adoption of disposable gloves by healthcare facilities in Australia and Japan due to hygiene concerns, accentuated by government regulations mandating their use. Continuous investments in R&D by corporations in South Korea and China led to the introduction of innovative, eco-friendly materials replacing traditional latex gloves. Sturdy demand from India and key ASEAN markets augmented the supply dynamics remarkably, with certain seasonal price escalation being absorbed without affecting consumption negatively.

Trends in the market were hallmarked by shifting preferences towards powdered gloves due to their easy donning. The online channel was favoured for procurement, especially remote businesses in China and India, which also aided the trend of bulk purchases. Partnerships between Indian and ASEAN manufacturing firms led to increased regional production, diminishing reliance on imports. Stricter enforcement of Occupational Safety and Health Administration (OSHA) standards in manufacturing and utilities industries across the region drastically increased usage. Consequently, the Principal Component Framework (PCF) implementation in Australia and Japan set forth stricter regulatory requisites for disposable gloves quality, setting benchmarks in healthcare customer satisfaction and safety.

Europe

In 2024, the disposable gloves market in Europe demonstrated marked dynamism, underpinned by a confluence of demand factors and evolving market trends. The resurgence of industrials and healthcare sectors across Germany, the United Kingdom, France, Italy and Spain drove demand, bolstered by heightened hygiene regulations in response to recent health crises. Investment in innovative, eco-friendly materials such as biodegradable nitrile, triggered by legislation in Nordic countries and Benelux, reshaped supply dynamics and pricing.

The market also witnessed discernible shifts in product preference, with buyers favoring powder-free gloves due to potential health risks associated with powdered variants. Increased online sales across Central & Eastern Europe reflected changing channel dynamics, as customers sought convenience amidst hectic schedules. Consolidation emerged as a strategic priority, with key players engaging in mergers and acquisitions to reinforce their market presence and harness cross-territory synergies. For instance, Ansell’s acquisition of Bohle Safety Gloves exemplified this trend. Stricter policy enforcement, especially in the healthcare and food service sectors, further spurred the demand for disposable gloves. The adoption of European Standards (EN) for medical gloves in France and Italy drove manufacturers to alter their production protocols, impacting the broader market landscape. Thus, the disposable gloves market in Europe, in 2024, was fundamentally shaped by intensified demand, product innovation, and strategic consolidation.

Latin America

In 2024, the Latin American disposable gloves market experienced substantial growth due to essential drivers and key trends. Increased healthcare investment in countries such as Brazil and Mexico led to higher consumption of disposable gloves, while stringent safety standards in sectors like food processing and pharmaceuticals across Argentina, Colombia, Chile, and Peru mandated their use. Moreover, heightened awareness of personal hygiene among consumers also contributed to this demand increase. Significantly, disposable nitrile gloves emerged as a dominant trend because of their superior chemical resistance and durability, indicating significant shifts in buyer preferences and technology adoption. However, the supply chains were disrupted due to the high dependence on Asian markets, affecting the overall market stability.

There was a visible trend in the e-commerce development across LATAM, where online platforms gained prominence as a dominant sales channel for disposable gloves. Partnerships and acquisitions also became a major trend, with companies aiming to expand their market presence and meet the rising demand. The enforcement of strict hygiene regulations, especially in the healthcare sector, also facilitated market growth. Overall, the disposable gloves market in LATAM, in 2024, was significantly driven by increased investment in healthcare, the implementation of safety standards across various sectors, and changing consumer behavior regarding hygiene.

Middle East & Africa

In 2024, the disposable gloves market in the Middle East and Africa demonstrated notable growth. Key drivers included heightened health awareness due to previous pandemics, implementation of strict health safety regulations - such as OSHA in Egypt - and increased investment in healthcare infrastructure particularly in Saudi Arabia and UAE. Technology adoption also played a significant role as many companies shifted towards nitrile gloves production due to their superior chemical resistance compared to latex.

The market experienced several trends in 2024. Consumer preference shifted towards powder-free gloves due to their hypoallergenic properties. This was evident particularly in the healthcare sector where disposable gloves are essential. Second, glove vending machines emerged in high-traffic retail areas and transit hubs around the UAE and Qatar, enhancing convenience and accessibility. Further, there was a marked inclination of industries, such as oil and gas in Nigeria and manufacturing in South Africa, to use heavy-duty disposable gloves, driving demand in these sectors. Lastly, partnership activities and mergers were observed, notably the alliance between major hospitals in Israel and glove manufacturers for a steady supply amidst increased demand. In 2024, the disposable gloves market in Middle East and Africa saw growth driven by health consciousness and regulatory enforcement, characterized by product innovation and new collaborations.

Recent Industry Developments

Latest market innovations, product launches, and strategic initiatives

April 2026

INTCO Medical expanded its non-latex glove portfolio with two new product lines: Syntex™ Synthetic Latex Gloves (formulated without sulfur and natural rubber latex proteins, passing EN455, EN374, FDA, and CE standards with up to 650% elongation) and Synmax Pro Gloves (featuring abrasion resistance approximately ten times higher than conventional nitrile gloves). INTCO's annual production capacity for disposable non-latex gloves reached 87 billion units by 2025, making it the world's largest manufacturer in this category.

April 2025

INTCO Medical launched its exclusive patented Syntex™ Synthetic Disposable Latex Gloves globally, offering high elasticity, puncture and chemical resistance, and a natural-latex-like feel while avoiding latex allergy risks.

Frequently Asked Questions