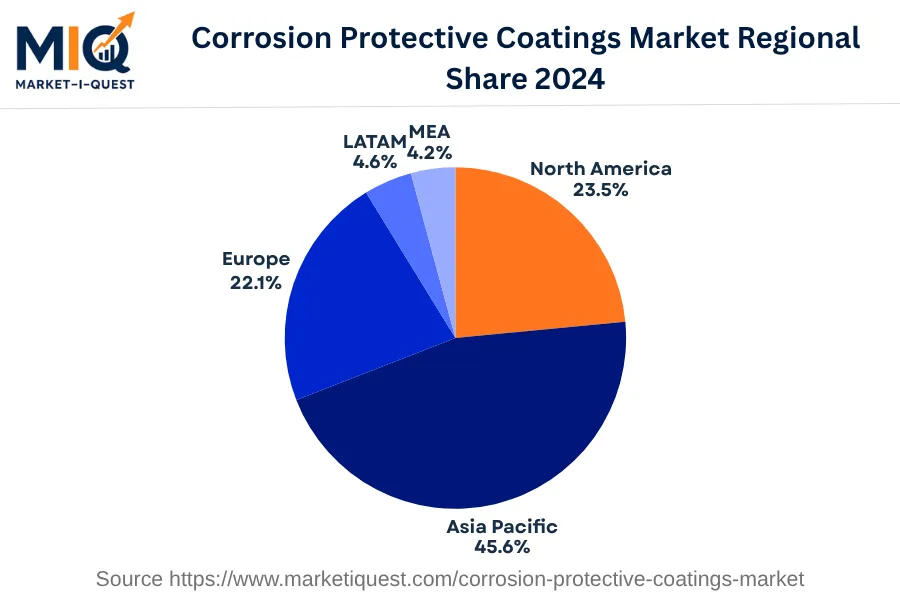
In 2024, the North American corrosion protective coatings market experienced robust growth, primarily driven by key industries such as manufacturing, oil and gas, utilities, and construction. Considerable investments by governments and private enterprises in infrastructure development acted as significant growth catalysts. Regulatory mandates enforced by governmental bodies across the U.S., Canada, and Mexico to use corrosion-resistant materials, contributed to the product demand. Technological advancements and adoption of nano-technology based anti-corrosion coatings also influenced the market dynamics.
Market trends exhibited a noticeable shift towards eco-friendly, water-based corrosion coatings, backed by heightened environmental consciousness and strict policies against volatile organic compounds emissions. Increased buyer preference for custom-made, long-lasting coatings witnessed a rise, thereby shifting product portfolios of major market entities. Direct-to-metal coatings gained prevalence as a cost-effective solution offering enhanced performance. Partnerships and M&A played a decisive role, aimed at expanding product offerings and consolidating market share. Finally, technology-driven methods for application and maintenance of these coatings gained popularity, altering distribution channels and customer engagement strategies. The market’s landscape was shaped by the needs of primary customer sectors; manufacturing, oil, and gas held significant demand shares followed by utilities and construction. These sectors, owing to their heavy metal usage, adopted corrosion protective coatings extensively to maintain infrastructure and equipment longevity. Canada's extraction sector and Mexico's manufacturing industry were key contributors to the regional market.