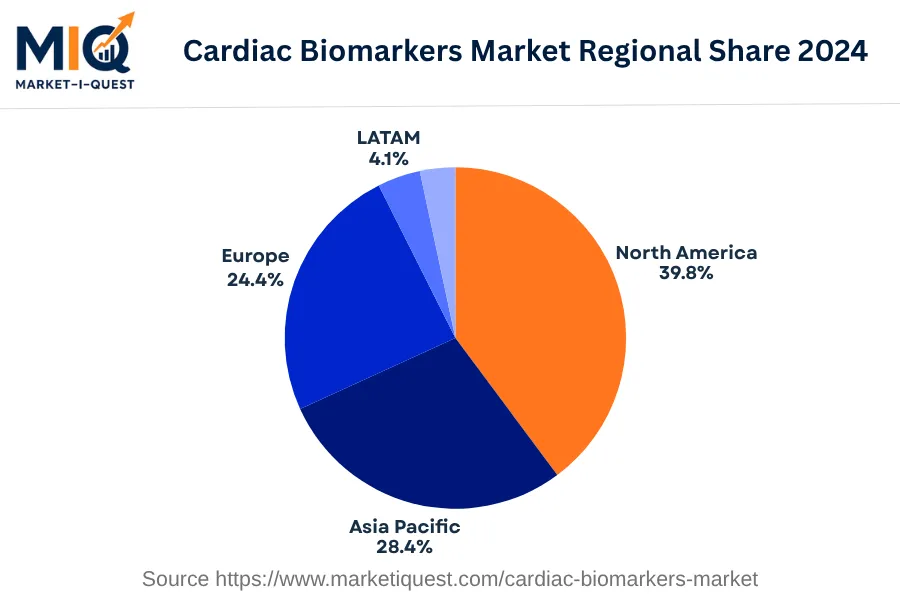
In 2024, North America's cardiac biomarkers market represented a critical segment in the region's diagnostic landscape.
Advancements in technology bolstered the demand, underlining improved precision in ischemic heart disease and acute coronary syndrome detection. Regulatory support, evidenced by U.S. Food and Drug Administration's approval of high-sensitivity troponin assays, served as another key driver by encouraging investments in research and development. Furthermore, increasing cardio-metabolic diseases incidences across the U.S., Canada, and Mexico spurned the need for accurate, prompt diagnostic measures, thereby fueling biomarker adoption.
Evolving patient awareness spurred changes in buyer behavior, with a noticeable lean toward preventive cardiac care, thus augmenting biomarker demand. Manufacturers responded accordingly with a shift in product development, focusing increasingly on multiplex biomarkers. This shift increased industry competition, instigating several mergers and acquisitions, such as Roche’s acquisition of Stratos Genomics, aimed at expanding capabilities. Diagnostic centers and hospitals emerged as the primary sectors utilizing cardiac biomarkers, owing to an increase in heart failure prevalence.
With technology adoption reshaping supply dynamics and rising health awareness altering buyer behavior, the cardiac biomarkers market in North America displayed a pattern of robust growth and innovation in 2024. This was particularly reflected within healthcare environments and regulatory bodies, punctuating their role in market progression.